Article on William Frey, Countrywide and the Servicer Safe Harbor Published in Lombard Street E-Journal

I am excited to report that FinReg21, a leading website on financial services regulation, has published a feature-length article by me, entitled Why Should Servicers Get a Safe Harbor? How One Investor’s Lawsuit Forced Bank of America to Seek Shelter in Washington, in its Lombard Street e-journal. Lombard Street is billed as “the first e-journal focused exclusively on financial services regulation in the 21st century.”

The article tells the story of William Frey and Greenwich Financial Services’ (“GFS”) legal challenge to Countrywide’s settlement with the Attorneys General, and how this lawsuit spurred the passage of the Helping Families Save Their Homes Act by Congress. The article pulls together many of the facets of this story that we have followed on The Subprime Shakeout, from the cycle of securitization that led to the subprime mortgage meltdown, to Washington’s push for loan modifications that led to Countrywide’s $8.4 billion settlement with Attorneys General from over 30 states, to the litigation and legislation that followed.
The last two sections of the piece go further, however. In the second-to-last section, I provide a legal analysis of how the Servicer Safe Harbor could run afoul of the Fifth Amendment’s Takings Clause if it operates to deprive GFS and other investors of their claims against Countrywide and other loan servicers. In the final section, I offer an alternative solution to the mortgage foreclosure crisis that would be more efficient and equitable than the blunt strokes that Washington has taken thus far.
I look forward to hearing any feedback that readers may have on this proposal or any other aspect of the article. Thanks to Doug Winthrop, Christine Camp, and Michael Ginsborg at Howard Rice for providing skillful editing and insightful feedback, and to Charley Spektor, and Marilyn Cohodas at FinReg21 for supporting critical, non-partisan analysis on this and other issues affecting the regulation of financial services.
Posted in consitutionality, Countrywide, FinReg 21, Greenwich Financial Services, Helping Families Save Homes, legislation, litigation, loan modifications, Servicer Safe Harbor, William Frey | Leave a comment

In Letter to Bank Regulators, Senators Reverse Course

Loan servicers’ star may be quickly fading in Washington. In a stunning reversal of course, Representative Barney Frank (D-Mass.), Chairman of the House of Representatives Committee on Financial Services, and Senator Christopher Dodd (D-Conn.), Chairman of the Senate Committee on Banking, Housing and Urban Affairs, issued a letter last week urging bank regulators to investigate whether mortgage servicers are resistant to modifying loans due to the issues surrounding their holdings in second lien mortgages. The Senators accused the servicers of “unwillingness…to extinguish their liens as required for participation in [the Hope For Homeowners] program, even in return for offers of reasonable compensation.” The letter also suggested that servicers may be overvaluing these assets on their balance sheets, resulting in “inadequate reserving” that skewed the financial picture of banks in general.

This warning shot across the servicers’ bow comes less than two months after Frank and Dodd marched the Helping Families Save Their Homes (HFSTH) Act through Congress waving the flag of servicer safe harbor. Though the HFSTH Act had the goal of reducing residential mortgage foreclosures by encouraging loan modifications, the bill also featured a Servicer Safe Harbor provision that provided legal immunity and generous incentives to mortgage servicers (the four largest being J.P. Morgan Chase, Wells Fargo Bank, Citibank and Bank of America) to modify mortgages and extinguish second liens. In the process, the bill dumped the costs of the modifications on the investors holding these mortgages, despite the fact that servicers were also frequently the lenders that pumped out these troubled loans in the first place. Apparently, these incentives have not been enough to induce servicers to participate in Hope For Homeowners, as Frank and Dodd are now turning on the banks they fought so hard to protect.

At the outset of the foreclosure crisis, Frank and other congressmen heaped the blame on bondholders, such as Bill Frey, who had simply insisted on their contracts being enforced. Because investors refused to allow the terms of the mortgages backing their investments to be modified willy-nilly, they provoked the ire of the House Financial Services Committee.

In this letter to Frey, Frank and five other congressmen expressed outrage that Frey would oppose their efforts to modify mortgages, and “strongly urge[d]” Frey to reverse his position. They further invited Frey to testify, but when Frey took them up on their invitation, they changed their minds. Deprived of the chance to be heard, Frey wrote this letter to the congressmen instead, pointing out that servicers “have financial incentives to avoid foreclosure…even if it creates greater losses for the mortgage investor.” More recently, Frey wrote this scathing op-ed piece in the Washington Times, criticizing the Safe Harbor and breaking down in concise terms the conflict of interest inherent in giving servicers the keys to the modification henhouse.

Though Frank and his colleagues may not have wanted to listen to Frey at first, it seems that they’re beginning to realize that servicers have strong motives to act contrary to the interests of investors, borrowers, and the rest of the country. Why it took politicians with a supposed expertise in this field so long to really delve into this issue is beyond me, but partisanship and campaign finance may certainly have come into play (after all, the Helping Families Save Their Homes Act was introduced by two congressmen high on Bank of America’s payroll).

While I’m encouraged that legislators appear to finally be unraveling the complexities involved in cleaning up these toxic assets, I’m disappointed that their first solution was to shout and wave a big stick in the hopes of pushing through their “plan.” Fixing a problem of this magnitude involves understanding the players and what makes them tick, not bullying people into compliance. And it starts with a willingness to listen without bias, not a coddling of constituency.

Posted in allocation of loss, Barney Frank (D-MA), BofA, Christopher Dodd (D-CT), Helping Families Save Homes, Hope For Homeowners, investors, loan modifications, Servicer Safe Harbor, William Frey | Leave a comment

New Evidence Shows Loan-to-Value Ratio Contributed Most Heavily to Mortgage Meltdown

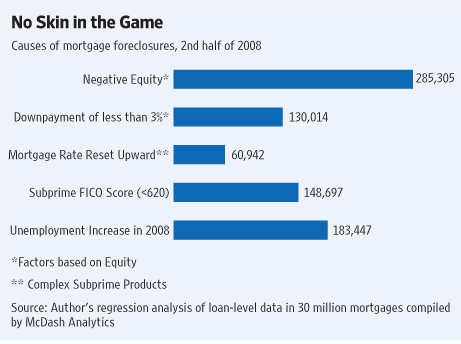
An article published in the Wall St. Journal this week by Stan Liebowitz posits a purportedly new take on the causes of the mortgage meltdown. Liebowitz’s analysis of recent data on millions of individual loans published by McDash Analytics, a component of Lender Processing Services Inc., compares the importance of several variables related to mortgage foreclosures. His conclusion? That the most important factor is whether the borrower has or ever had positive equity in the home (see graphic at right).

A borrower’s equity in a home is often expressed in terms of loan-to-value (“LTV”) ratio, or the amount of the first lien the borrower took out on the home compared to the appraised value of the home. So, if a borrower took out a $450,000 loan on a home valued at $500,000 (and made a $50,000 down payment), the LTV ratio on the mortgage would be 90%. An even better statistic is the combined loan-to-value (CLTV) ratio, which measures the amount of all loans taken out on the home compared to the value of the home, and thus includes second liens and HELOCs in the calculation. During the late years of the housing bubble, it became increasingly popular for borrowers to take out one loan on the first 80% of the value of the home, and a second loan for the rest, which meant that borrowers had no skin in the game, and often led to negative equity situations when housing prices crashed.
LTV and CLTV ratios were always one of the most important factors for gauging the riskiness of a loan. Thus, Liebowitz’s conclusion is not surprising. Borrowers with little or no equity in their home are much more likely to walk away from the loan when times get tough, whereas those who have put a significant amount of their own money into their home are more likely to try to work out a payment plan or put their home on the market. But from this rather unremarkable finding, Liebowitz attempts to proffer a much broader revelation and debunk the “common narrative” that subprime lending and stated income loans were significant causes of the foreclosure crisis.
While Liebowitz may be correct that the impact of subprime lending and stated income loans on foreclosures was more limited than the “common narrative” suggests, the truth is that this type of lending was symptomatic of the drastic loosening in underwriting standards that preceded the housing collapse of 2007. And, as Liebowitz recognizes, this loosening was enabled and fueled by a government- and Wall St.-backed campaign to artificially increase homeownership levels beyond where they should have been. If borrowers were really able to afford the homes that they were purchasing, they would have made sizable down payments so as to earn better interest rates over the life of their loans.
Instead, because the government was providing tax and other incentives to expand lending, Wall St. was making considerable profits from securitizing and selling these additional loans, and borrowers were happy to delude themselves into thinking that if they qualified for a loan, they could afford to own the home, this country experienced an explosion in irresponsible lending and borrowing that led us inevitably to the credit crunch we’re experiencing today. Subprime was a symptom of this unsustainable growth in lending and a symbol of the excesses this culture engendered. Ask yourself if you were a lender under ordinary lending conditions, would you give a borrower with a blemished credit record a loan for the full amount of the house, without requiring any down payment or an income tax return?
This is where Liebowitz and I, and most other experts on this subject, can most readily agree. Stronger underwriting standards are indeed necessary to return lending to the rational risk-assessment process it was intended to be.
The tougher issue is what to do about the current pool of “toxic assets,” backed by distressed loans, that are freezing up our credit markets. This solution is more nuanced and complex, and involves a loan-by-loan assessment. If the borrower cannot afford and could never have afforded the home, there must be a foreclosure. If the borrower was misled into the loan, the servicer should help effect a loan modification, the cost of which should be born by the lender or broker who acted in a predatory or fraudulent manner. And for everyone else who borrowed reasonably but who, due to the current financial crisis or a change of circumstances, cannot now afford to make their payments, we must decide as a society what makes the most sense.
If foreclosures are so costly that we’ve decided that society as a whole would benefit from large-scale loan modifications to reduce the foreclosure rate, then taxpayers should be prepared to foot that bill rather than sticking investors (or any other insular group) with the loss.
Thank you to Michael Ginsborg at the Howard Rice Library for passing along Liebowitz’s thought-provoking article – IMG.
Posted in allocation of loss, foreclosure rate, irresponsible lending, lending guidelines, loan modifications, loss causation, LTV, negative equity, stated income, subprime, toxic assets, Wall St. | Leave a comment

Latest Gatekeeper Litigation: City of San Buenaventura Sues Deloitte Over WAMU Subprime Collapse

Following on the heels of the lawsuits against KPMG by New Century’s debtors for contributing to the collapse of the mortgage giant, accounting firm Deloitte & Touche (D&T) and the officers and directors of Washington Mutual Bank (WAMU) have been sued by the City of San Buenaventura, California for failing to disclose the bad financial condition and poor risk management practices at WAMU (USDC, Northern District of California, Case No. 3:09-cv-01980 JSW). The complaint, filed by law firm Cotchett, Pitre & McCarthy, alleges that the plaintiff bought a note issued by WAMU, but that the bank’s true financial condition was hidden by WAMU’s officers, directors and its auditor. WAMU promptly defaulted on the note, allegedly due to losses from its portfolio of subprime loans.

Similar complaints have been filed by Cotchett in recent months, including a suit by the Monterey County Investment Pool (available here), which names D&T and WAMU’s officers and directors as defendants and alleges fraud, negligent misrepresentation, and breach of fiduciary duty for losses resulting from WAMU’s debt offerings, and a suit by the San Mateo County Investment Pool against Lehman Brothers and Ernst & Young along the same lines.

The suit by the City of San Buenaventura is the latest of what I have termed “gatekeeper litigation,” meaning lawsuits against ratings agencies, accounting firms, due diligence firms and other “gatekeepers” who were supposed to be minding the store and ensuring that financial services companies were accurately representing their own risks and those of their debt offerings. All too often during the housing boom of the last decade, and especially in 2006-2008, investors placed a high degree of reliance on the approbation of these gatekeepers as to the health of companies or the investment-grade status of their securities. As we now know, these gatekeepers were often paid by the companies they were hired to vet, and as a result were incentivized to overlook financial red flags or outright infirmities.

Of the various gatekeepers, ratings agencies have faced the greatest maelstrom resulting from their role in the subprime crisis. It will be interesting to see how successful this gatekeeper litigation will be at tying investment losses to the negligence or fraud of the overseers (see this well-rounded article on lawsuits against the ratings agencies and my prior discussions regarding loss causation in general) and whether such litigation will result in changes to the legal treatment of these entities (see this early article by Kevin LaCroix of the D&O Diary and the debate over the First Amendment rights of ratings agencies in the WSJ) or in the manner in which they are compensated.

Posted in accounting, auditing, Deloitte and Touche, Ernst and Young, gatekeeper litigation, incentives, KPMG, Lehman Brothers, loss causation, ratings agencies, subprime, WaMu | Leave a comment

Obama Proposes Sweeping Reforms For Financial Regulation

Just last weekend, in discussing the current financial crisis with friends, I expressed concerns that in the panic to unfreeze the credit markets and stabilize the economy, our government would continue to simply throw money at the problem, while ignoring the systemic changes that must take place to prevent this credit crunch from reoccurring in another form some ten years down the road (anyone remember the S&L Scandal?). I likened the government bailouts, TARP funds and even early legislation, like the Helping Families Save Their Homes Act, to mere tourniquets to stop the economic bleeding, when what the financial system really needed was reconstructive surgery.

Just days later, the Obama Administration unveiled what the President called “a sweeping overhaul of the financial regulatory system, a transformation on a scale not seen since the reforms that followed the Great Depression.” And while the fact that lawmakers, financial institutions and consumer groups are already challenging the plan comes as no surprise, I share their concerns that this plan is more like a series of band-aids than a skeletal fortification for the financial system.

News of the plan first broke on Monday, when secretary of the Treasury Tim Geithner and National Economic Council director Lawrence Summers jointly published an op-ed piece in the Washington Post, entitled, “A New Financial Foundation.” The article outlined the plan in broad strokes and stated that, “[t]he goal is to create a more stable regulatory regime that is flexible and effective; that is able to secure the benefits of financial innovation while guarding the system against its own excess.” On Tuesday, President Barack Obama released an 88-page document detailing the plan, which he introduced in a speech to industry executives and senior officials in the East Room of the White House on Wednesday.

The plan is ambitious in scope, if not in depth. It addresses virtually every sector of the financial industry, including derivatives, mortgages, capital requirements, insurance companies and hedge funds. The most welcome components from my perspective are also among the most obvious. The plan requires lenders to retain a percentage of the loans they originate, in an effort to ensure that lenders are properly incentivized to originate quality loans instead of simply selling off the loans and transferring the risk to third parties. As I’ve discussed in the past, forcing lenders to have some skin in the game is essential to an effective securitization market, but the question remains whether a mere 5% will be enough to do so (not to mention the question of whether the lender’s 5% will be representative of the overall pool).

Another necessary, if somewhat obvious proposal, is to merge the functions of the Office of Thrift Supervision into the Office of the Comptroller of the Currency. This consolidation has been explicitly recommended by watchdog organizations such as the Center For Responsible Lending and hinted at by the Office of the Inspector General at the Department of Treasury (see my prior post on the collapse of IndyMac Bank). While this reform should help prevent “regulator-shopping” and the lax oversight such shopping engenders, the plan stops short of a substantial consolidation of banking regulators, as the Fed, the OCC and the FDIC continue to play various roles in this area.

Which leads me to my greatest concern regarding Obama’s financial overhaul, and the concern generating the most attention in Congress thus far: that the plan bestows upon the Federal Reserve an expanded role of overall risk regulator in the brave new financial world. Wait, you may be thinking, is this the same Fed that kept interest rates unsustainably low throughout the housing boom that fueled the run-up to this crisis? The same Fed that is supposedly “independent” because it is not beholden to the President or the voters, yet evinces a striking proclivity towards protecting certain favored banks at the expense of others in times of crisis? The same Fed that is about as Federal as Federal Express? Yes, that’s the one.

Obama’s plan gives the Fed even broader power and responsibility to police the financial system against the same excesses that it was supposed to guard against and didn’t over the past ten years. The logic behind this move? “The president believes there is not a better way to prevent and manage a future crisis without putting the authority in one place,” said Geithner. “We have to make a choice. I do not believe there is a plausible alternative that provides accountability, credibility and gets to the core of the problem.”

In other words, oversight must be consolidated, and the Fed is, to paraphrase Churchill, the worst option, except for all of the others. The fact that the administration can’t think of anyone better to police the financial system than a group of unelected former bankers who retain close ties to the industry, doesn’t exactly instill confidence. And for those of us who believe the Fed, which subject to few, if any, constitutional checks and balances, already has too much power in our current system of governance, this plan to hand over even more authority to this quasi-private enterprise smacks of both passing the buck on our tough regulatory decisions and dangerously shifting the balance of power in economic regulation and enforcement. I therefore urge lawmakers, when considering Obama’s plan, to consider each of its proposals carefully and on its own merits to ensure that we do not lose this opportunity to make meaningful changes and prevent the next credit crisis from shattering our economic system.
Posted in Barack Obama, Center for Responsible Lending, Federal Reserve, Government bailout, incentives, legislation, lenders, oversight, recession, regulation, TARP, Timothy Geithner, underwriting practices | Leave a comment