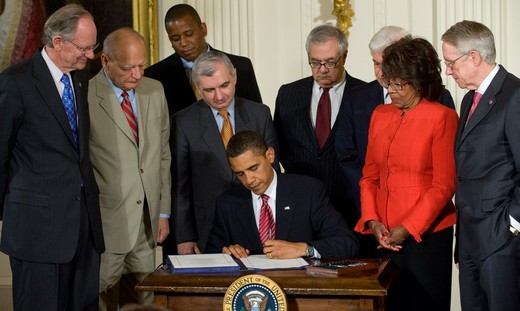
Obama Signs Helping Families Save Their Homes Act Into Law, Complete With Servicer Safe Harbor

On May 21, President Barack Obama signed the Helping Families Save Their Homes Act into law (P.L. 111-22), including the controversial “Servicer Safe Harbor” provision that relieves servicers of their contractual liabilities for modifying loans without investor approval. The House had passed the Senate’s version of the bill on May 19 by a 367-54 margin, paving the way for the legislation to be forwarded to the President for signing.

Though the final version of the Servicer Safe Harbor is slightly more watered-down than the original version proposed in the House, the legislation still operates to undermine mortgage securities investors’ important contract rights and relieve from liability the very entities (the lenders who originated the loans, sold the loans off into securitizations and continued to receive fees for servicing the loans on behalf of the investors) who were often most culpable for creating the toxic securities that have been freezing up our credit markets for over a year.

You can view the full text of the law here, but the following are the key excepts from the final version of the Servicer Safe Harbor:

SEC. 201. SERVICER SAFE HARBOR FOR MORTGAGE LOAN MODIFICATIONS.
…

(b) Safe Harbor- Section 129A of the Truth in Lending Act (15 U.S.C. 1639a) is amended to read as follows:
`SEC. 129. DUTY OF SERVICERS OF RESIDENTIAL MORTGAGES.
`(a) In General- Notwithstanding any other provision of law, whenever a servicer of residential mortgages agrees to enter into a qualified loss mitigation plan with respect to 1 or more residential mortgages originated before the date of enactment of the Helping Families Save Their Homes Act of 2009, including
mortgages held in a securitization or other investment vehicle–
`(1) to the extent that the servicer owes a duty to investors or other parties to maximize the net present value of such mortgages, the duty shall be construed to apply to all such investors and parties, and not to any individual party or group of parties; and
`(2) the servicer shall be deemed to have satisfied the duty set forth in paragraph (1) if, before December 31, 2012, the servicer implements a qualified loss mitigation plan that meets the following criteria:
`(A) Default on the payment of such mortgage has occurred, is imminent, or is reasonably foreseeable, as such terms are defined by guidelines issued by the Secretary of the Treasury or his designee under the Emergency Economic Stabilization Act of 2008.
`(B) The mortgagor occupies the property securing the mortgage as his or her principal residence.
`(C) The servicer reasonably determined, consistent with the guidelines issued by the Secretary of the Treasury or his designee, that the application of such qualified loss mitigation plan to a mortgage or class of mortgages will likely provide an anticipated recovery on the outstanding principal mortgage debt that will exceed the anticipated recovery through foreclosures.
`(b) No Liability- A servicer that is deemed to be acting in the best interests of all investors or other parties under this section shall not be liable to any party who is owed a duty under subsection (a)(1), and shall not be subject to any injunction, stay, or other equitable relief to such party, based solely upon the implementation by the servicer of a qualified loss mitigation plan.
…
`(g) Rule of Construction- No provision of subsection (b) or (d) shall be construed as affecting the liability of any servicer or person as described in subsection (d) for actual fraud in the origination or servicing of a loan or in the implementation of a qualified loss mitigation plan, or for the violation of a State or Federal law, including laws regulating the origination of mortgage loans, commonly referred to as predatory lending laws.’ (emphasis added)

While this language does not provide servicers the sweeping relief from liability featured in the original House version of this bill (H.R. 1106), this safe harbor provision certainly muddies the waters as to whether investors can force servicers to repurchase loans they modify without showing that the expected net present value (NPV) from modification exceeds the expected NPV from foreclosure. Instead, it allows servicers to “reasonably determine” on their own when the anticipated recovery from modification will “likely” exceed the anticipated recovery from foreclosure, irrespective of any NPV analysis. This could create a significant misalignment of incentives where the servicers decide to modify a first-lien mortgage while protecting the second-lien mortgage they’ve retained on their books.

Most importantly, the bill does little to recognize that servicers were often the same entities that lent irresponsibly to borrowers who could not afford to pay back the loans, and should be held culpable rather than given safe harbor (let alone paid to breach their contractual obligations). As the ABS Investor Advocate points out, the saving grace of the Servicer Safe Harbor provision is the language that the servicer may not be held liable “based solely upon the implementation by the servicer of a qualified loss mitigation plan” combined with the “Rule of Construction” protecting investors’ rights to pursue repurchases if the servicer violated a predatory lending law or originated a loan in a fraudulent manor. Though it should be a given that a servicer can’t be relieved from liability for fraud and predatory lending by modifying the loan, the fact that this language was inserted only after the first version of the bill passed the House shows how slow legislators have been to recognize the role that servicers played in engendering the mortgage crisis.

Still, the bill is silent as to whether servicers may continue to be held liable or forced to repurchase loans that they originated negligently, a much more common issue with a much lower threshold of proof. During the housing boom, lenders often looked the other way and ignored red flags regarding the legitimacy of borrower statements or their ability to pay back loans, in direct conflict with their representations and warranties that they would follow definite and precise guidelines ensuring sound underwriting. If investors are no longer able to enforce their contract rights to put such loans back to the lenders whose irresponsible lending helped to create this crisis, this bill would create an injustice of vast proportions.
Posted in Barack Obama, Helping Families Save Homes, incentives, investors, irresponsible lending, legislation, loan modifications, Servicer Safe Harbor, toxic assets | 1 Comment

Grais & Ellsworth Launches ABS Investor Blog

On Monday, New York law firm Grais & Ellsworth jumped into the legal blogosphere with a new law blog on the fallout from the subprime mortgage crisis entitled “The ABS Investor Advocate.” According to named partner David Grais, the blog’s purpose is, “to give ABS [asset backed securities] investors a forum and thereby to help protect their very legitimate interests.”

The blog should become another excellent resource for those seeking to keep tabs on the ever-changing legal landscape and proliferation of litigation stemming from this crisis. Like my firm, Howard Rice, Grais & Ellsworth will be able to offer a unique perspective on these issues due to its representation of Bill Frey and Greenwich Financial Services in their class action lawsuit against Countrywide and their involvement in Frey’s lobbying efforts in Washington to foment opposition to the Servicer Safe Harbor.

The blog’s early posts include commentary on the Goldman Sachs settlement with the state of Massachusetts, Grais‘ “Five Reasons Why ‘Servicer Safe Harbor’ Will Be Bad for America” (discussed in a prior post here), and a comparison of the text of the House and Senate Versions of the Servicer Safe Harbor (which references a post in the Subprime Shakout on the Senate’s general approach of downplaying the Safe Harbor provision of the Helping Families Save Their Homes Act).

Perhaps this blawg will become the voice for mortgage-backed securities investors that has been generally missing from the national debate on loan modifications. I look forward to keeping tabs on this new resource at the heart of the subprime shakeout.

[Editor’s Note: the ABS Investor Advocate blog appears to have been taken down.  If anyone has any information on this development, please contact me – IMG]

Posted in Grais and Ellsworth, Greenwich Financial Services, Helping Families Save Homes, investors, legislation, litigation, loan modifications, Servicer Safe Harbor, subprime, William Frey | Leave a comment

Helping Families Save Their Homes Act (S. 896) Passes Senate, Awaits Approval From House

The Senate passed a version of the Helping Families Save Their Homes Act (S. 896) on Wednesday by a vote of 91-5. The bill will now go back before the House of Representatives, which can adopt it, amend it, send it back to the Senate, or convene a conference committee where both houses of Congress can work out their differences.

One major difference between the bills passed by the Senate and the House is that the version passed by the House in early March (H.R. 1106) contained a bankruptcy cram-down provision that would allow bankruptcy judges to modify principal balances of residential mortgage loans; S. 896 has no such provision.

Unfortunately, both pieces of legislation contain the short-sighted “Servicer Safe Harbor” provision that allows servicers to override their contractual obligations to bondholders to repurchase mortgages that they modify. Interestingly, this provision has been downplayed by those who supported the bill, including Senator Chris Dodd (D-CT), who sponsored the bill in the Senate. The announcement of the passage of the bill on Dodd’s website heralds the bill as providing “more tools to borrowers and banks to help prevent foreclosures” while making it “easier for homeowners and loan servicers to use those tools.” The announcement makes no mention of the Servicer Safe Harbor or the fact that it would shift losses from loan modifications from the banks who originated the loans to the bondholders who negotiated contract clauses to avoid them.

Other Senators who actually discuss the safe harbor provision don’t seem to fully understand it. For example, Senator Mel Martinez (R-FL) notes on his website that, “the safe harbor provision will be especially valuable in giving mortgage servicers the ability to modify home loans while protecting the future of the residential mortgage credit markets.” Martinez ignores the fact that servicers already have the ability to modify home loans. Indeed, James B. Lockhart, the director of the Federal Housing Finance Agency, was recently quoted in an insightful article in the Wall St. Journal as saying that servicers “can work within the present system [without lawsuit protection] and get a lot of loan modifications done.” Servicers are, however, currently incentivized to do so only when they can maximize the long-term value of the loan. Far from protecting the long term future of the residential mortgage credit markets, the Servicer Safe Harbor provision would discourage future investment in RMBS by sending a message to potential investors that their contractual safeguards can be disregarded at any moment by a stroke of the legislature’s pen.

You can track the progress of this bill as it winds its way through Congress with the new Legislation Tracker widget on the sidebar to the right.

Posted in allocation of loss, bankruptcy cramdown, Christopher Dodd (D-CT), Helping Families Save Homes, incentives, investors, legislation, loan modifications, Servicer Safe Harbor | 1 Comment

Amendment to Restrict Servicer Safe Harbor Rejected By Senate

On Tuesday, the U.S. Senate rejected a measure that would have limited the “Servicer Safe Harbor” provision of the “Helping Families Save Their Homes Act,” which aims to protect servicers from lawsuits over their modifications of residential mortgage loans. The amendment to narrow the safe harbor, sponsored by Senator Bob Corker (R-TN), was defeated by a margin of 63 to 31.

The defeated amendment would have provided some mortgage bondholders, such as Bill Frey, the right to sue mortgage servicers if they lowered a borrower’s monthly payments in violation of servicers‘ contract obligations. As discussed in prior posts, the largest mortgage servicers are banks that were often responsible for originating these predatory or unsound loans in the first place, but which sold the loans into securitizations and maintain only servicing rights as to these loans. As servicers, these entities receive a fee for interfacing with borrowers and collecting payments, and they have contractual obligations to maximize returns for securities holders. Instead, servicers are being pressured (and have other financial incentives) to modify mortgages to help keep borrowers in their homes, a campaign that would cost investors billions.

But the news is not all bad for bondholders who are attempting to force servicers to bear the costs of their irresponsible lending. A number of major media outlets, including the Wall Street Journal, have now picked up this story thanks to recent lobbying efforts by Frey and others in Washington. As the Journal article shows, congressmen and the news media are beginning to understand that helping servicers at the expense of bondholders is not only inequitable and bad for future investment in the United States, but it might even run afoul of the Fifth Amendment’s Takings Clause.

Posted in costs of the crisis, Helping Families Save Homes, homeowner relief, incentives, investors, irresponsible lending, legislation, Servicer Safe Harbor, William Frey | Leave a comment

Bondholders Battle Back Over Servicer Safe Harbor

Back in early March, without much fanfare, the U.S. House of Representatives passed H.R. 1106, entitled the “Helping Families Save Their Homes Act of 2009”, which contained a “Servicer Safe Harbor” provision that would allow servicers to disregard bondholders’ contract rights when modifying mortgages. It now appears that the bill will not fly so easily through the Senate (keep tabs on the progress of this bill here at govtrack.us or here at thomas.loc.gov).

On March 25, 2009, Bill Frey, the head of hedge fund Greenwich Financial Services LLC, gave a talk in Washington to more than 30 money managers with stakes in the $6.7 trillion mortgage bond market, warning them that government efforts to assuage the housing crisis will undermine debt contracts and do more harm than good. Also presenting at the bond investor conference, which was attended by, among others, representatives from Royal Bank of Canada’s Voyageur Asset Management Inc. and Thrivent Financial for Lutherans, were David Grais, the lawyer who represents Frey in his suit against Countrywide (which may have prompted this bill), and Laurie Goodman, an analyst at Amherst Securities and UBS AG’s former fixed income research chief. According to this interesting report from Bloomberg, as a result of this meeting, a group of investors with residential mortgage-backed securities (RMBS) holdings totaling more than $100 billion hired Patton Boggs LLP, Washington’s biggest lobbying firm, to gear up for the fight in Washington over the pending legislation.
As part of this new lobbying effort, Grais and his firm, Grais & Ellsworth LLP, have issued a press release entitled “Five Reasons Why ‘Servicer Safe Harbor’ Would be Bad for America.” This release does an excellent job of explaining the perverse consequences of the bill, while capturing in straightforward terms the various reasons why mortgage bondholders oppose this legislation, despite its purported purpose of “helping families save their homes.” For one, bondholders negotiated for the valuable contract rights at issue, which impose the cost of modifications on servicers (Grais identifies these servicers as “mainly the Big Four Banks, Bank of America, Citibank, JP Morgan and Well[s] Fargo”), as a precondition to investing their money into RMBS. Bondholders secured these rights because they knew that modifications would otherwise come out of their bottom line, not from that of the servicers who had the discretion and authority to conduct loan modifications. Allowing servicers to abrogate these rights would unfairly place the financial burden of modifications on bondholders and thereby discourage future investment in the RMBS market.
A second reason is that, while servicers don’t hold many of the senior or first-lien mortgages on their books, they do hold many junior or second-lien loans. By law and/or contract, second liens are often required to be modified before first liens. Allowing servicers to modify first liens before or in lieu of second liens improves these banks’ bottom lines at the expense of their investors.
Third, the legislation offers cash incentives of $1,000 per loan modified and other incentives to the servicers, allowing the entities that made a fortune from lending and then passing off loans that borrowers couldn’t afford to further profit from going back and attempting to correct their mistakes.
When Grais runs into a bit of trouble is when he claims that the Servicer Safe Harbor “would not help homeowners.” Grais’ argument is that servicers will often increase the principal balance of loans they modify by adding the extra fees they charge borrowers who fall behind. He contrasts this with investors’ plan for modifications, which he claims will “reduce principal to give homeowners equity.” What Grais doesn’t tell us is how many mortgages will be modified if the Servicer Safe Harbor is passed versus under the investors’ plan. Ultimately, most homeowners would choose to stay in their homes, even at the expense of an increase in principal, over having to leave because they couldn’t afford their current mortgage payments. And while the investors’ plan may favor lowering principal balances, the likely consequence will be a higher monthly payment than under the banks’ modification plans.
In the end, there is little argument that the Servicer Safe Harbor will likely result in more mortgages being modified than before, something that investors, banks, politicians and homeowners would all agree is a good thing. The real fight is over who should pay for these modifications, and Grais and Frey would be wise to keep the focus on this debate. Investors believe that either the government or the banks should bear the costs, while the banks would like nothing more than to place the burden on the investors. Washington now appears likely to be the one to decide this issue, and as is often the case (unfortunately) when it comes down to politics, the answer will be in large part a result of how much money has been spent on lobbying and campaign contributions. Just look at the two politicians who introduced the “Helping Families Save Their Homes Act” in the House, Paul E. Kanjorski (D-PA) and Michael N. Castle (R-DE). Bank of America (which now owns Countrywide) was the second biggest contributor to Castle’s campaign during the 2007-2008 election cycle, making Castle one of the top 10 beneficiaries of BofA last year (behind only presidential candidates). Kanjorski was the second biggest recipient of Countrywide campaign contributions since 1989. Clearly, BofA expects (and has received) a tangible return on its investment.
Yet, there is already evidence that bondholders’ lobbying efforts are countering those of the big banks and paying significant dividends. Though the mainstream media had up to this point largely ignored the Servicer Safe Harbor issue, Gretchen Morgenson, a columnist for the New York Times, published a column last week discussing the “unintended consequences” of the Helping Families Save Their Homes Act and loan modifications in general. Morgenson notes, correctly, that while “big-time speculators and market sophisticates” make up part of the group of investors who would be harmed by this bill, the group also includes ordinary individuals who invested in mutual funds and other professionally managed accounts that acquired RMBS as part of their portfolios. Ultimately, if votes mattered more than dollars (a debatable proposition), it would be this argument, with its populist appeal, that
would carry the day in Washington.

Thank you to David Proman and Chris Corio who contributed helpful insight and research to this story – IMG.
Posted in BofA, Countrywide, Greenwich Financial Services, Helping Families Save Homes, irresponsible lending, legislation, loan modifications, lobbying, Servicer Safe Harbor, William Frey | 2 Comments