
When I posted last, I was preparing to speak on a Federal Bar Association panel amid growing concerns of a reckoning coming in the CMBS and broader commercial real estate (CRE) space, and mounting interest in the potential litigation to come. What I have learned during that enlightening panel, and since, is that many thought leaders in this space share our belief that the commercial market’s reliance on “extend and pretend” is unsustainable, and red flags of prevalent misconduct continue to emerge like cracks spreading across a frozen lake.
Today, I wanted to provide updates on one of the more significant CMBS putback cases that we are currently following, as well as alerts regarding two new putback cases that were filed within the last few months.
Wells Fargo v. JPM II Updates
Both my initial comeback post about the cracks in the CRE market and my subsequent deep dive into the application of RMBS putback precedent to the burgeoning CMBS putback space have highlighted Wells Fargo, National Association, as Trustee of JPMCC 2019-MPF v. JPMorgan Chase Bank, N.A., et al., Case No. 25cv1943 (SDNY, filed March 10, 2025) (“Wells Fargo v. JPM II”), as a canary in the CRE coal mine, signaling the widespread presence of the toxic fumes of fraud. This case only continues to offer interesting clues about the state of commercial lending over the past several years.
On September 18, 2026, the parties to this dispute over JPM’s obligation to repurchase the at-issue mortgage—a $481 million loan backed by a portfolio of 43 multifamily properties (the “Loan”)—filed their letters for leave of Court to brief motions for summary judgment (“MSJ”), identifying the key issues they seek to resolve ahead of trial. In its Letter to Court Requesting Leave for Summary Judgment Briefing (Dkt. 105) (“Plaintiff’s MSJ Letter”), Wells Fargo revealed interesting evidence uncovered during discovery and unveiled a wrinkle to their contractual claims that could impact the strength and viability of both the instant case and CMBS putback claims generally.
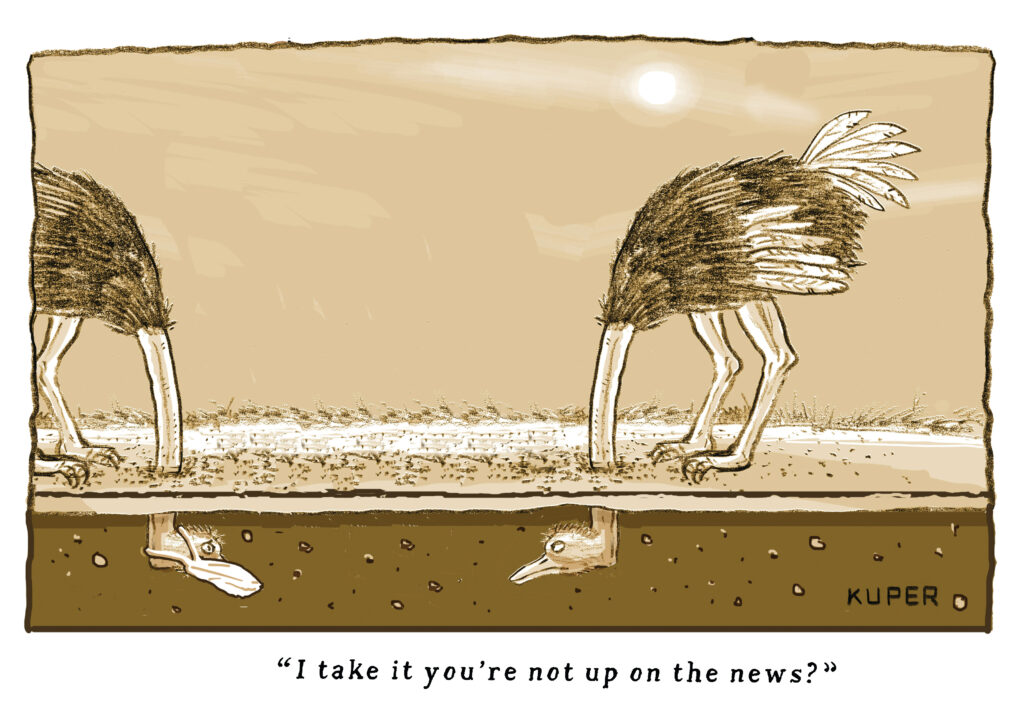
As I discussed in my last update on this case, JPM’s primary argument on its since-denied motion to dismiss focused on the position that Wells Fargo’s repurchase claim failed to satisfy the knowledge qualifier included in the case’s central loan-level representation and warranty (“R&W”). Here, the knowledge qualifier preceding R&W No. 4, the primary R&W at issue in the case, regarding the absence of Events of Default in the underlying Loan, states, “to the best of the Seller’s Knowledge (as defined below) after due inquiry….” In its motion to dismiss at the outset of this case, JPM argued that this qualifier limited its liability to only those breaches where it had actual knowledge of the breach at the time the CMBS trust closed. This is an argument I’ll refer to as the “Ostrich Defense” – in essence, that as long as JPM heard and saw no evil, it was permitted to bury its head in the sand without running afoul of any representations requiring actual knowledge. In denying JPM’s motion to dismiss, Judge Ho reasoned that a mere “indicia [of evidence] that would allow the inference of actual knowledge” was sufficient to establish actual knowledge at the dismissal stage of the case, and that such indica was present here. WF v. JPM II, Decision and Order on Motion to Dismiss (Dkt. 87) at 7. But, of course, the Judge was required to draw all reasonable inferences in the plaintiff’s favor at the motion to dismiss stage.
Recognizing that JPM will continue to lean on this defense, which will be more difficult to defeat at the MSJ stage, Wells has made the knowledge qualifier a central focus of its proposed MSJ, both in noting what its discovery into JPM’s actual knowledge has revealed and in calling into question whether JPM can even take advantage of this defense. As to the latter, Wells seeks to shift the focus of the Court from the language of the knowledge qualifier itself to the language that surrounds it.
Namely, Wells Fargo trains its sights not on the “Seller’s Knowledge” portion of the knowledge qualifier, but on the “after due inquiry” portion, arguing that this creates an affirmative obligation for JPM to have conducted a reasonable inquiry, and that JPM cannot escape liability due to its lack of knowledge if it failed to conduct such an inquiry. Plaintiff’s MSJ Letter at 3. In doing so, Wells seeks to turn the Ostrich Defense on its head, arguing that JPM must prove it actually sought to acquire knowledge before it can use its lack of knowledge as a defense.
Namely, Wells Fargo trains its sights not on the “Seller’s Knowledge” portion of the knowledge qualifier, but on the “after due inquiry” portion, arguing that this creates an affirmative obligation for JPM to have conducted a reasonable inquiry, and that JPM cannot escape liability due to its lack of knowledge if it failed to conduct such an inquiry. Plaintiff’s MSJ Letter at 3. In doing so, Wells seeks to turn the Ostrich Defense on its head, arguing that JPM must prove it actually sought to acquire knowledge before it can use its lack of knowledge as a defense.
This threatens to throw a wrench into JPM’s plans to limit its liability to what it actually knew, by arguing that the Court should not even reach that question if JPM buried its head in the sand and never made a reasonable inquiry to learn the truth about any existing or potential Events of Default in the first place. Whether this representation creates an affirmative obligation and, if so, what type of inquiry was required of JPM under these circumstances will be one of the thornier and more novel issues in this case that Judge Ho will have to decide.
In addition, Wells has submitted a significant amount of new evidence with its MSJ Letter based on discovery into JPM’s actual knowledge, including both deposition transcripts and documentary evidence. One of the most interesting witnesses deposed in the case is Borko Milosev, an individual who conducted due diligence on behalf of the Borrower, the Chetrit Group. Mr. Milosev’s deposition testimony was noteworthy in that he indicated that JPM was specifically told that its underwriting on the Loan was based on incorrect and fraudulent information, yet JPM still used the false information in its underwriting and investor disclosures, to the astonishment of Chetrit’s advisors. See Plaintiff’s MSJ Letter at 2; id., Exs. 19, 25-26.
Even after Chetrit’s advisers agreed to point this out to JPM before closing, Wells Fargo alleges that JPM never requested nor received corrected financial information, and proceeded to use the same inaccurate financial statements to securitize the loan. Id. at 2, Exs. 19, 22. Thereafter, Wells alleges that Milosev described the performance of the properties as “a total sh*t show” immediately following securitization due to the existence of far more vacancies and far less rental income than what was originally reported, which were precisely the sort of discrepancies Wells alleges that a proper underwriting process was meant to catch. See Plaintiff’s MSJ Letter at 2; id., Ex. 19.
As far as documentary evidence goes, Wells Fargo submitted JPM’s own internal CMBS underwriting guidelines from 2016, which purported “to set forth the standards, requirements, and procedures to be followed, and forms and documents to be used, by J. P. Morgan CMBS [], JPMorgan Chase Bank, N.A. [], and any other J.P. Morgan entity in connection with the origination and closing of commercial mortgage loans intended to be distributed within the capital markets.” Id., Ex. 13 at 3. These requirements and procedures include, “[c]omplet[ing] a reconciliation of actual cash receipts (bank deposits) to the monthly rents used for underwriting” when underwriting loans collateralized by multifamily properties. See id., Ex. 13 at 38.
Wells Fargo alleges that JPM did not follow its own underwriting guidelines, including diligence checklist items, when it failed to obtain and review bank records. Plaintiff’s MSJ Letter at 2. Wells Fargo further argues that these guidelines were required to be followed in order for JPM to perform the “due inquiry” required of it by R&W No. 4, particularly given the issues it alleges JPM knew to exist with respect to the Loan. Id. This could be powerful evidence in Wells Fargo’s favor, though it remains to be seen whether Judge Ho finds that JPM actually warranted that it would follow these guidelines (in connection with its “after due inquiry” R&Ws or otherwise) as to this Loan, which was acquired for securitization rather than originated by JPM itself.
Milosev described the performance of the properties as “a total sh*t show” immediately following securitization due to the existence of far more vacancies and far less rental income than what was originally reported, which were precisely the sort of discrepancies Wells alleges that a proper underwriting process was meant to catch.
Naturally, JPM filed its own Letter to Court Requesting Leave for Summary Judgment Briefing (Dkt. 106) (“Defendant’s MSJ Letter”), in which it both responded to issues raised by Wells Fargo and raised issues of its own. In particular, JPM advanced various counterarguments regarding the implications of “after due inquiry,” and noted that it plans to address the issue in its own offensive MSJ. Defendant’s MSJ Letter at 3. JPM further stated that it plans to argue that it has no obligation to perform any “due inquiry” in the first place because to create such an obligation out of that language would “eviscerate” the knowledge qualifier itself. Id. While this argument may have some surface appeal (and has at least some support in the law), it’s not clear it will resolve the issue in JPM’s favor on these facts.
A requirement that a Seller have actual knowledge is not “eviscerated” or rendered superfluous by a requirement that it conduct an inquiry. These are two distinct concepts, and it would be reasonable for parties to contract in such a way that a Seller was only responsible for certain defects of which it had actual knowledge, provided that it had at least conducted a reasonable inquiry. Interpreted in that manner, the Seller is still protected by such a provision against liability for defects that it did not actually discover through reasonable diligence (though I note that JPM also argues in its Letter that due inquiry is different than “due diligence,” with the former being apparently less stringent). As a policy matter, Wells Fargo’s interpretation of R&W No. 4 also seems like the most reasonable approach to allocating responsibility as to potential Events of Default, as it prevents a responsible party from engaging in (or at least disincentivizes) willful ignorance, while not placing upon it the onerous burden of responsibility for every potential or actual Event of Default that was not reasonable discoverable.
Not to be outdone, JPM submitted with its MSJ Letter a significant amount of its own discovery into its knowledge and offered a competing narrative about what the evidence suggests. In particular, JPM has presented the testimony of one of its own employees (Brian Baker), maintaining that JPM was unaware of any fraud or inconsistencies in the financial data with respect to the Loan at the time the CMBS closed. However, it seems to me that the word of an employee from a company that has already admitted to wrongdoing (The Chetrit Group) will be generally more credible and believable than the word of an employee who continues to be employed by a company that is in the process of defending itself and has not admitted to any wrongdoing (JPM). Further, testimony like Mr. Baker’s will likely be insufficient to win the day in the face of the documentary evidence presented thus far that seems to confirm JPM’s actual knowledge of these issues.
Ultimately, the above summarizes just a fraction of the evidence that has been filed in this case in connection with the MSJ Letters, and those interested are encouraged to dig further into the deposition transcript excerpts and documentary evidence now available on the docket. In addition, both parties, as well as Meyer Chetrit, have now filed letters in opposition to the initial MSJ Letters. There should be no shortage of interesting legal battles and developments worth following and reporting upon as this case continues. We expect the Court to be back shortly with a response to the MSJ Letters, either scheduling a hearing to discuss the issues to be briefed or simply granting leave to proceed with summary judgment briefing on the issues already identified.
In particular, I think the outcome of the dispute over the interpretation of the knowledge qualifier will be the decision most impactful on the broader legal landscape in CMBS putbacks, as many CMBS deals have similar knowledge qualifiers around key R&Ws (a feature frequently added to CMBS 2.0 after the Global Financial Crisis), and they frequently include some version of the “after due inquiry” language. If the Court agrees that “after due inquiry” creates an affirmative obligation to perform an inquiry sufficient to make the related R&W in the first place, how many Sellers would be exposed to liability simply because they did not make any reasonable inquiry into the basis for various R&Ws? And if the Court agrees that the inquiry required here is for JPM to underwrite CMBS loans it purchases pursuant to its own internal policies and procedures (as Wells has argued), what are the odds that banks in a similar position could meet that standard? Would we expect that the same banks that drove the explosion of defective RMBS issuance back in the mid-2000s would suddenly begin conducting careful due diligence on loans being originated or securitized in the commercial space in the mid-2010s and into the 2020s?
Update on New CMBS Putback Cases
Beyond the developments in WF v. JPM II, I wanted to flag that we are seeing an increasing number and scope of other CMBS-related cases hitting civil dockets in the past few months. From a rise in commercial foreclosures and guarantor actions, to new actions by borrowers against special servicers, to actions by CMBS trustees against borrowers for fraud, and even to actions for breach of contract by lenders against appraisers, this litigation space is experiencing an acceleration in the volume and type of cases being filed. These filings collectively signal the existence of the most important factor for the viability of investor actions – widespread, systemic fraud in the origination and securitization process.
Though each type of case supplies its own interesting piece of the puzzle, we will continue to follow most closely the investor-driven CMBS putback cases as likely the most well-established avenue available for investors to recover existing or forthcoming losses in the CRE space. And in that regard, there are two additional CMBS putback actions that were filed within the last couple months that readers may find of interest.
Computershare Trust Company, National Association, as Trustee of WFCMT 2024-5C1 and Lead Note Holder under Co-Lender Agreement v. LMF Commercial, LLC, Case No. 26-cv-07165 (S.D.N.Y., filed Aug. 21, 2026) (“Computershare v. LMF”) is a putback action brought in connection with a $53,000,000 loan collateralized by multifamily commercial property located in Euclid, Ohio. The underlying claims are straightforward, though based on seemingly brazen acts on the part of the borrower and/or significant negligence on the part of the lender. Computershare alleges that falsified insurance certificates were submitted as part of the related loan file and that the required property insurance was not in place on the subject property, breaching various R&Ws (including, potentially, a version of the No EOD R&W discussed above, which did not include the “after due inquiry” language). As obtaining property insurance is a standard requirement in nearly every commercial lending deal, the alleged absence of property insurance raises significant questions about why insurance was not able to be obtained. The allegations of falsification of insurance certificates suggest that whatever that issue was, it was known and intentionally obscured.
Computershare Trust Company, National Association, as Trustee of BMO 2024-5C5 v. Starwood Mortgage Capital LLC, Case No. 655096/2026 (N.Y. Sup. Ct., filed September 4, 2026) (“Computershare v. Starwood II”) is a putback action brought in connection with a $46,850,000 loan collateralized by multifamily commercial property located in Houston and Pasadena, Texas. Computershare alleges that the subject loan securitized into BMO 2024-5C5 was never in a senior position, as required, and that when the subject property became distressed and foreclosure occurred, the loan was completely wiped out. How a securitized and purportedly senior loan can somehow end up subordinated to a more senior loan is beyond me, and suggests a significant breakdown in the gatekeeping process, both for commercial lending and CMBS issuance. It seems certain there’s a story here worth investigating.
We’ll continue to follow these and other interesting filings in the commercial real estate space in the coming months. As always, I welcome any questions or input from folks interested in these developments and the potential opportunities they engender.
Author’s Note: Special thanks again to Nathan van Loben Sels for his significant contributions to the research and writing of this post.
Isaac Gradman is a partner at Perry Johnson Anderson Miller & Moskowitz in Santa Rosa, California, where he specializes in structured finance litigation, bankruptcy and restructuring, investment fraud, and other complex commercial and financial disputes.