Focus of New Regulation Should Be On Securitization

The election of Barack Obama as the presumptive 44th President of the United States promises to usher in an era of increased regulation of the financial markets pursuant to Obama’s platform of economic reform. So far, many commentaries on the financial crisis, including this blog, have focused on the fact that subprime and Alt-A loans were made in an economically irresponsible manner, resulting in a default rate much higher than anticipated. This would suggest that financial regulation aimed at preventing this problem from reoccurring should focus on curbing lending to those who are unlikely to be able to repay their loans.

While this may be a good idea in general, new evidence has emerged that the extent of the financial crisis is not adequately explained by a higher-than-expected default rate among subprime and Alt-A loans. This article from the Economic Times reports that while losses in the financial system from all loans (accounting for the potential snowball effect that defaults have on home prices) have amounted to $425 billion, the financial system has suffered additional losses of $945 billion on investment in securities.

The article further explains that the reason why this second category of losses has been so large is that the accounting treatment of securities is so different from that of loans. Traded securities must be valued at market prices for accounting purposes, whereas loans need not be “marked to market” and regulatory norms provide the basis for their value. It thus stands to reason that the evaporation of the mortgage-backed securities market would create a situation where these securities became essentially valueless for accounting purposes, thereby underrepresenting the true value of the securities if calculated based on the value of the loans backing them up.

A further cause of these losses, not mentioned in the Economic Times article, is the fact that many banks and other financial institutions were holding these securities on their books as reserves, which form the benchmark for how much money these banks could lend out. For every dollar in reserves held by a bank, it is allowed to lend ten dollars. Thus, when the value of the reserves shrinks by a dollar, the bank must call in ten dollars’ worth of outstanding loans (including loans made to other banks). One can then see how the sudden and complete evaporation of value of these securities would cause a spiraling liquidity crisis in the financial markets, as the money supply shrinks at an exponential rate.

Based on this evidence, Obama and legislators would be well-advised to focus their regulatory sights on the use and accounting of asset-backed securities in the financial markets, and not just on the irresponsible borrowing and lending that may have been the initial cause of this crisis.
Posted in accounting, Alt-A, banks, Barack Obama, broader credit crisis, causes of the crisis, lenders, mortgage market, regulation, securities, securitization, subprime | Leave a comment

Clinton Breaks Down the Credit Crisis

I happened to catch Bill Clinton on the Late Show with David Letterman earlier this month and was surprised at how much substance was contained in the interview. I encourage you to read the full text of Clinton’s explanation of the causes of the credit crisis, as it is concise, straightforward and relatively accessible.

But is it correct? Clinton generally perceives the broader credit crisis as an issue of too much money floating around without enough good investment opportunities for it to flow into. Clinton touches on the fact that the Fed kept interest rates low following the burst of the tech bubble, in an effort to keep economic activity going and prevent a recession. This cheap money then flowed into residential real estate, which Clinton says was the only sector of the economy demonstrating real growth – 40-50% in the first five years after 2001. This overinvestment in real estate, combined with an increase in leverage and insufficient regulation was what caused this crisis, according to Clinton. In other words, it was a problem of incentives.

I ran this explanation by a number of my friends in the investment banking and hedge fund world over the weekend, and they generally agreed that the driving force behind this crisis was an improper incentive structure, and a resulting liquidity crisis when housing prices began to level off. But they placed the blame much more squarely in the court of the federal government, something Clinton tried to downplay.

For one, keeping interest rates low after the bursting of the tech bubble makes perfect sense to help stimulate investment and prevent recession. But, at some point, those interest rates have to be normalized, otherwise the cheap cash leads to overinvestment in risky ventures, e.g. subprime mortgages.

Moreover, a number of government programs provided incentives for potentially unqualified people to take out mortgages, including tax breaks for homeownership, legislation encouraging lending to minorities and low-income borrowers, and the rise of subprime lending and its concomitant looser lending guidelines. All the while, there was a ready secondary market for mortgage-backed securities and other derivatives based on such loans, provided by quasi-governmental enterprises Fannie Mae and Freddie Mac.

My banking friends thus came to generally the same conclusion that Clinton did – this was a problem of perverse incentives – but felt these incentives were fueled in large part by the government. Naturally, they defended financial institutions by arguing that if one lender did not make that loan to Mr. Unqualified Borrower, someone else would. As a famous financial maxim goes, “the markets can stay irrational a lot longer than you can stay solvent.”

Now, this is not to say that lenders and borrowers did not play a role by participating in ill-advised or ill-intentioned loans. I’ve made the point several times that this system would not have collapsed so completely had the foundation been built on sound lending. But, we can’t expect financial institutions to make moral decisions – they are institutions that operate to maximize profits. It is up to government to legislate and enforce the law to properly incentivize institutions to act within legal limits. As is becoming more readily apparent, in order to fix this crisis and prevent it from reoccurring, we must start from the top-down by creating a market with the proper incentives and making sure government is working to encourage sound investment.

Posted in banks, Bill Clinton, causes of the crisis, cheap money, Fannie Mae, Federal Reserve, Freddie Mac, incentives, interest rates, legislation, lenders, liquidity, overinvestment, subprime | Leave a comment

Potential Jurors Unfriendly to Mortgage Lenders?

As reported by Peter Page in the National Law Journal (subscription required), a survey completed earlier this month of adults eligible for jury service found that potential jurors overwhelmingly held plaintiff-oriented perceptions with respect to suits against mortgage lenders.

“Nearly 90 percent of those surveyed believe subprime lenders abandoned sound lending practices,” the article reported. “More than half said subprime lenders knowingly lent money to people unlikely to afford the payments.”
While I was surprised at the high percentage of respondents who were aware that banks had abandoned sound lending practices, what was most interesting to me was the discrepancy between that number and the number who believed lenders had knowingly lent money to people who couldn’t pay it back. The former category suggests that banks were merely negligent, while the latter suggests intentional, predatory lending. But, both categories suggest incompetent underwriting, which in reality would never have persisted or been in the lenders’ self-interest if not for the securitization mechanism that allowed them to pass along most of the responsibility for their poor decisions (see very interesting article on downfall of U.S. financial institutions from U.K. perspective).

The survey seemed to focus on hypothetical cases by individual homeowners against mortgage lenders. As I read the article, because of our representation at Howard Rice of a large mortgage insurer, I naturally began to think about how juror reactions might change in a case by an insurer against one of these lenders. As some of the quotes in the article suggest, these responses may have been fueled in part by an emotional connection to a homeowner pitted against a large corporation. It would be interesting to see how these numbers would change with respect to hypotheticals involving two corporations. Still, on balance, the survey shows that the public is largely aware of the excesses by lenders that contributed to this crisis, and that lenders would be well-advised to consider all of their legal options short of trial.

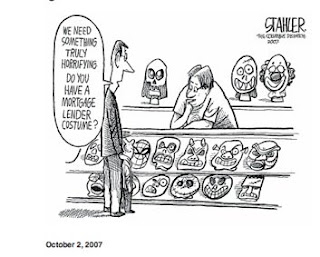
(Thanks to nationally syndicated political cartoonist and Editorial Cartoonist for the The Columbus Dispatch, Jeff Stahler, for this appropriate cartoon)

Posted in causes of the crisis, Howard Rice, jury trials, lenders, litigation, mortgage insurers, predatory lending, public perceptions, securitization, subprime, underwriting practices | Leave a comment

Howard Rice Issues Press Release Featuring Attorney Blogs

In a bit of shameless self-promotion, I note that The Subprime Shakeout was featured, along with Steve Mayer’s blog, The California Constitution, in a press release issued by Howard Rice Nemerovski Canady Falk & Rabkin about the firm’s promotion of “thought-leadership” amongst its attorneys. Thank you to Howard Rice for its continued support of this endeavor to understand the subprime crisis and its ramifications.

Posted in Howard Rice, press, subprime | Leave a comment

Wikipedia Subprime Timeline a Comprehensive (and Opinionated) Resource

I just discovered the Wikipedia Subprime Crisis Impact Timeline that provides a great resource to those trying to understand what this crisis is and how we got here. The timeline spans 40 years from 1968 to the present, including the most recent entry as of this posting: “October 8 [, 2008]: White House considers taking ownership stakes in private banks as a part of the bailout bill. [108] Warren Buffett and George Soros criticized the original approach of the bailout bill.[109][110].”

Notably, the timeline pulls no punches regarding the many causes of this meltdown. It begins, appropriately, with the conversion of Fannie Mae from a government entity to a stand-alone GSE in 1968 (to purchase and securitize mortgages to facilitate liquidity in the primary mortgage market) and the creation of GSE Freddie Mac in 1970 (to buy mortgages on the secondary market, pool them, and sell them as mortgage-backed securities to investors on the open market). While I agree that Freddie and Fannie played no small role in fomenting the atmosphere that eventually led to this crisis, the choice to begin the timeline here seems to place the blame squarely at the feet of the GSEs.

But, the GSEs are not the only quasi-federal entities called out in this fascinating summary. In one of my favorite entries, Wikipedia cites an article from Barron’s Magazine for the following entry: “2003-2007: The Federal Reserve failed to use its supervisory and regulatory authority over banks, mortgage underwriters and other lenders, who abandoned loan standards (employment history, income, down payments, credit rating, assets, property loan-to-value ratio and debt-servicing ability), emphasizing instead lender’s ability to securitize and repackage subprime loans.[22]”

Then, there’s this entry from October 15-17, 2007: “Both Fed chairman Ben Bernanke and Treasury Secretary Hank Paulson expressed alarm about the dangers posed by the bursting housing bubble; Paulson said ‘the housing decline is still unfolding and I view it as the most significant risk to our economy. … The longer housing prices remain stagnant or fall, the greater the penalty to our future economic growth.’[40]” This statement is remarkable in hindsight, as the Fed and Treasury failed to take any significant action to alleviate this crisis until September 2008, when they took over Freddie and Fannie and proposed the “Emergency Economic Stabilization Act.” Of course, this did not prevent Paulson from saying that the proposal was “an urgent matter, and we need to move quickly” as he called for the immediate passage of the largest government bailout since the Great Depression.

Check out Wikipedia’s subprime crisis timeline as this shakeout unfolds for some interesting perspective on the regulatory and legislative missteps that brought us to this point.

Posted in bailout, banks, Ben Bernanke, causes of the crisis, Fannie Mae, Federal Reserve, Freddie Mac, Hank Paulson, legislation, regulation, securitization, subprime, takeover, timeline, Treasury, Wikipedia | Leave a comment